Why More Black Founders Are Crossing Over Into Venture Capital
With funding to Black-led startups stuck near historic lows, a growing number of founders are stepping into investor roles — hoping to reshape who gets backed from the inside.
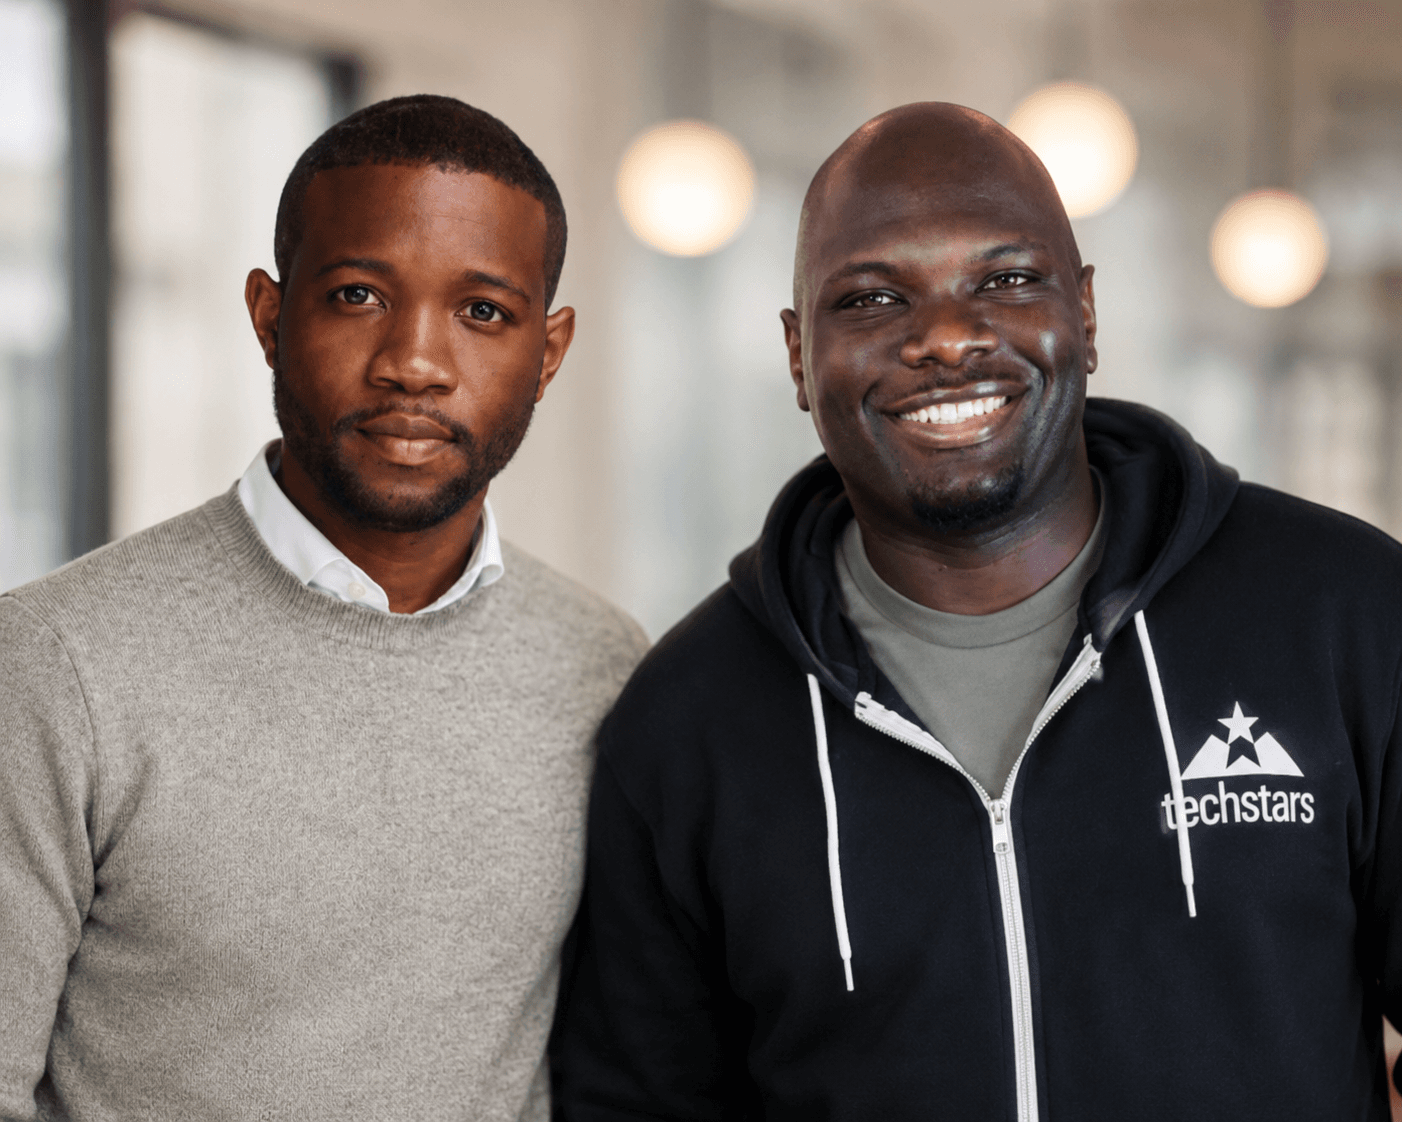
When the numbers refuse to move, some founders stop waiting for the system to change and decide to become part of the system instead. That's the path two entrepreneurs took after years of grinding through fundraising rounds that rarely seemed to weigh them on the same scale as everyone else.
A Funding Gap That Won't Close
The broader backdrop here is stark. Capital flowing to startups with at least one Black founder has consistently represented a tiny sliver of total venture dollars, and last year's figure ranked among the thinnest in recent memory. Even with an uptick in early 2026 driven largely by a strong first quarter, the structural gap remains wide. That persistent shortfall is exactly what pushed a handful of founders to rethink their role in the industry entirely — moving from the pitching side of the table to the checkbook side.
From Pitching For Capital To Allocating It
One founder built an extended-warranty company in the Midwest, eventually raising close to $30 million before an acquisition closed out the venture. He describes early fundraising as brutal, compounded by factors well beyond product or traction. Rather than treat that friction as a dead end, he leaned into learning the unwritten rules of venture capital itself — eventually joining one of his own former backers as an investor and entrepreneur-in-residence. The shift gave him a front-row view of patterns he'd only sensed as a founder, and it ultimately inspired him to build an education platform aimed at giving early-stage entrepreneurs a clearer map of how funding decisions actually get made.
A second founder followed a parallel but distinct route. After building two companies — one offering software tools for personal trainers, another an online learning platform co-founded with a well-known actor — he grew frustrated watching peers get treated as unfinished products needing to prove everything upfront, while other founders received years of patient, developmental capital. That observation pushed him toward angel investing, where he discovered just how much of venture decision-making boils down to pattern recognition rather than pure merit.
Venture capital wasn't built to be fair — it was built to generate returns. Real change won't come from rewriting the economics, but from diversifying the people in the room who decide what a fundable founder looks like.
Networks, Not Just Bias, Drive The Gap
Perhaps the more nuanced insight from these crossover investors is that exclusion in venture capital rarely looks like a deliberate decision to shut anyone out. Because the industry runs heavily on referrals, alumni networks, and existing investor circles, homogeneous networks tend to reproduce homogeneous deal flow almost automatically. Many investors, in this view, simply never encounter a wide enough range of founders to begin with — which makes the fix less about individual intent and more about who gets access to the rooms where deals originate in the first place.
- Funding to Black founders remains a thin slice of the market. Despite a modestly stronger start this year, the long-term share of venture dollars reaching Black-founded startups has fallen sharply over the past few years.
- Some founders are responding by becoming investors. Moving to the other side of the table offers a clearer view of how funding decisions are actually made — and where the system can be nudged toward fairness.
- Pattern recognition, not malice, drives much of the gap. Investors often default to backing founders who resemble past successes, which can unintentionally narrow who gets serious consideration.
- Coaching and patience function as a form of capital. Founders who don't fit familiar molds are frequently asked to arrive "finished," while others are given time and support to grow into the role.
- Diversifying who writes the checks may matter more than changing the rules. Both founders suggest that broadening the perspectives inside investment committees could do more than any structural overhaul of venture economics.