The Air Taxi Company That Skipped the Venture Treadmill and Went Straight to Wall Street
Archer Aviation listed publicly with fewer than 100 employees, long before it had a certified aircraft. Founder Adam Goldstein argues it was the only fundraising route that matched the size of the problem — and it has since pulled in close to $4 billion.
Most founders treat an IPO as the finish line — the reward for a decade of private rounds, a proven product and predictable revenue. Archer Aviation ran the sequence backwards. It went public with a skeleton crew, an aircraft still in development and a regulatory path nobody had walked before, because its founder concluded that the conventional venture ladder simply could not carry the weight of what he was trying to build.
The Product Is a Shortcut Through the Sky
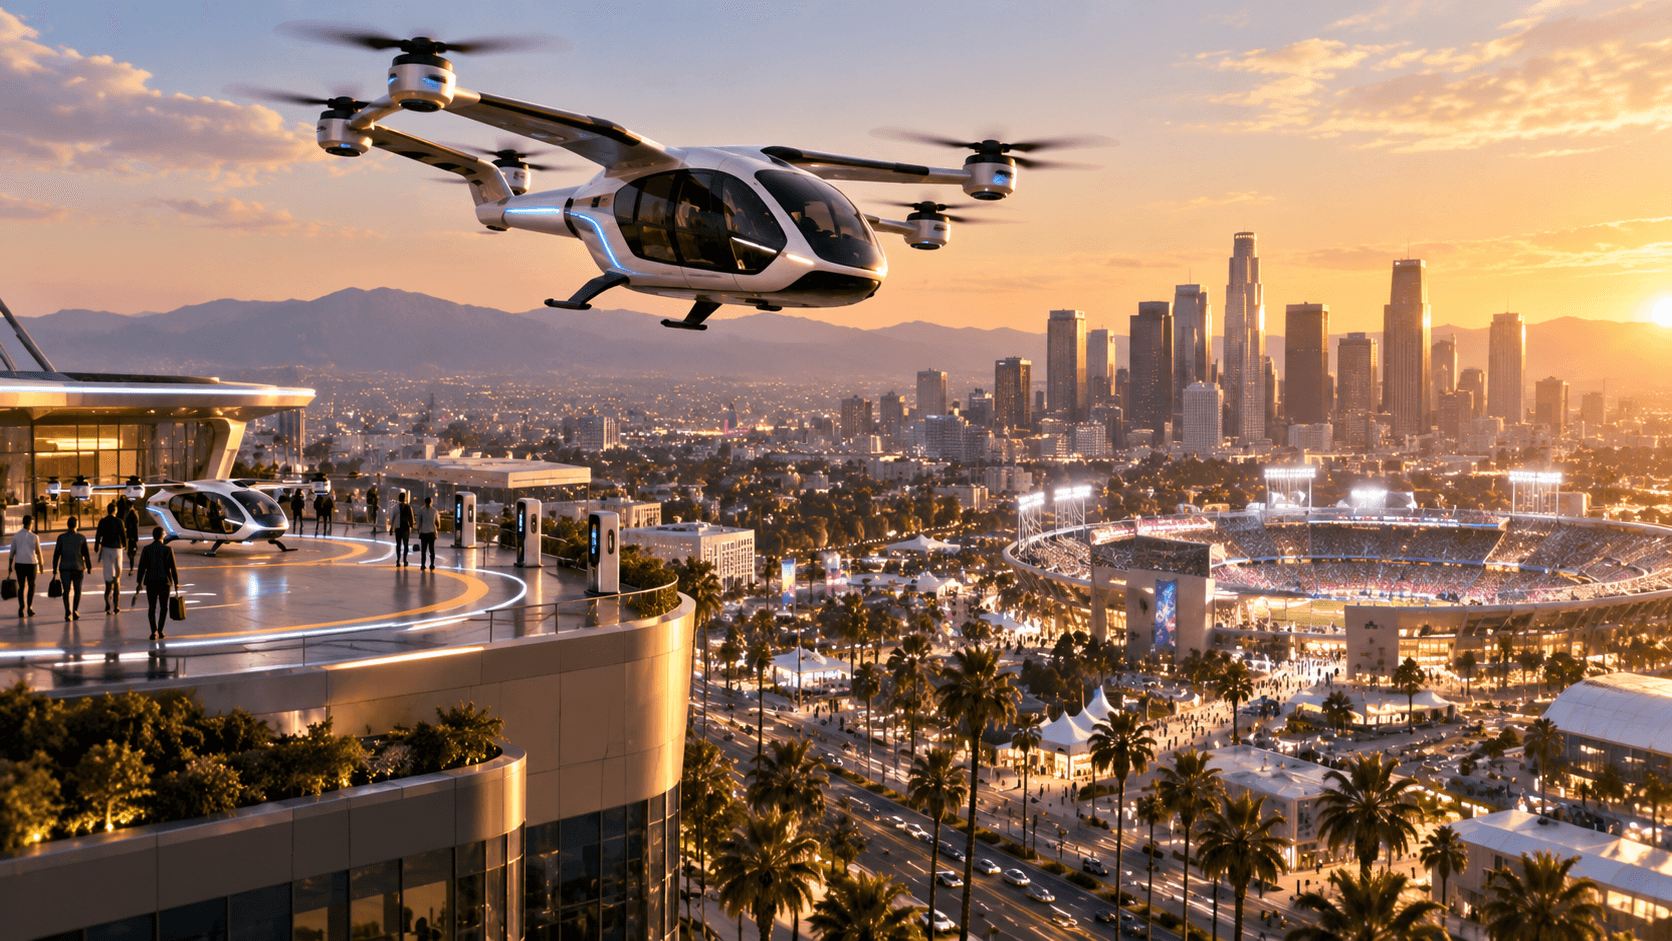
Archer builds electric vertical takeoff and landing aircraft — eVTOLs — designed for short urban hops. The pitch is deceptively simple: take a journey that eats ninety minutes in traffic and compress it into a ten-to-fifteen-minute flight. Airport-to-city transfers are the obvious opening use case, the trip where ground congestion inflicts the most damage on the most valuable hours.
The company has been selected as the exclusive air taxi provider for the upcoming Los Angeles Olympics, which gives it something most deep-tech startups never get: a fixed deadline, a global audience and a city whose traffic is itself a punchline. It is also developing the technology for defense applications, a second market that sits on largely the same airframe and propulsion work.
Why $100 Million at a Time Was Never Going to Work
Software founders raise to find product-market fit. Hardware founders raise to survive the years before anything can legally be sold. Certifying an entirely new category of aircraft means wind tunnels, test fleets, manufacturing lines and a regulatory process measured in years, all of it burning capital before a single paying passenger boards.
Goldstein's realisation was that rounds of $50 million or $100 million, spaced out over years of dilution and board negotiations, were simply the wrong instrument. The gap between what venture rounds deliver and what aerospace certification costs is not a gap you close with better pitch decks. So rather than stack a dozen private rounds, he took the company to the public markets while it still had fewer than a hundred people on the payroll — and has since raised close to $4 billion.
Preparation Comes Long Before the Listing
The part founders tend to underestimate is how much groundwork an early listing demands. Goldstein's argument is that a company has to be built for public-market scrutiny well ahead of actually pursuing a listing — governance, reporting discipline, narrative clarity and the ability to explain a decade-long roadmap to investors who can sell on any given Tuesday. Timing matters enormously too. Windows open and close, and a company that is not already prepared cannot move when one opens.
He also believes the door may be reopening for earlier-stage companies to access public markets — a shift that would matter well beyond aviation. Climate infrastructure, nuclear, robotics, space and advanced manufacturing all share the same structural problem: capital requirements that outstrip what private rounds comfortably supply.
Pick a Problem Worth Decades
Running through the whole conversation is a piece of founder advice that has nothing to do with financing mechanics: choose a problem you are willing to spend decades on. An early public listing only makes sense if the founder intends to still be there when the aircraft is certified, the routes are operating and the original thesis is finally tested in the open. Anyone optimising for a five-year exit would find the same strategy unbearable.
The financing structure a founder chooses is really a statement about how long they plan to stay. Going public before you have a product only works if you intend to be there a decade later, still answering for it.
- The listing was a financing decision, not an exit. Archer went public with fewer than 100 employees specifically to access capital at a scale private rounds couldn't match.
- Nearly $4 billion has followed. That figure is the real argument for the strategy — and the reason other capital-hungry hardware founders are studying it.
- The product proposition is time. Turning a 90-minute road journey into a 10-to-15-minute flight is the value users would actually be paying for.
- An Olympic deadline is both pressure and proof. Being named the exclusive air taxi provider for the Los Angeles Games gives the company a hard date and an unmissable showcase.
- IPO readiness is built years in advance. Governance, reporting and narrative discipline have to exist before the window opens, because windows don't wait.